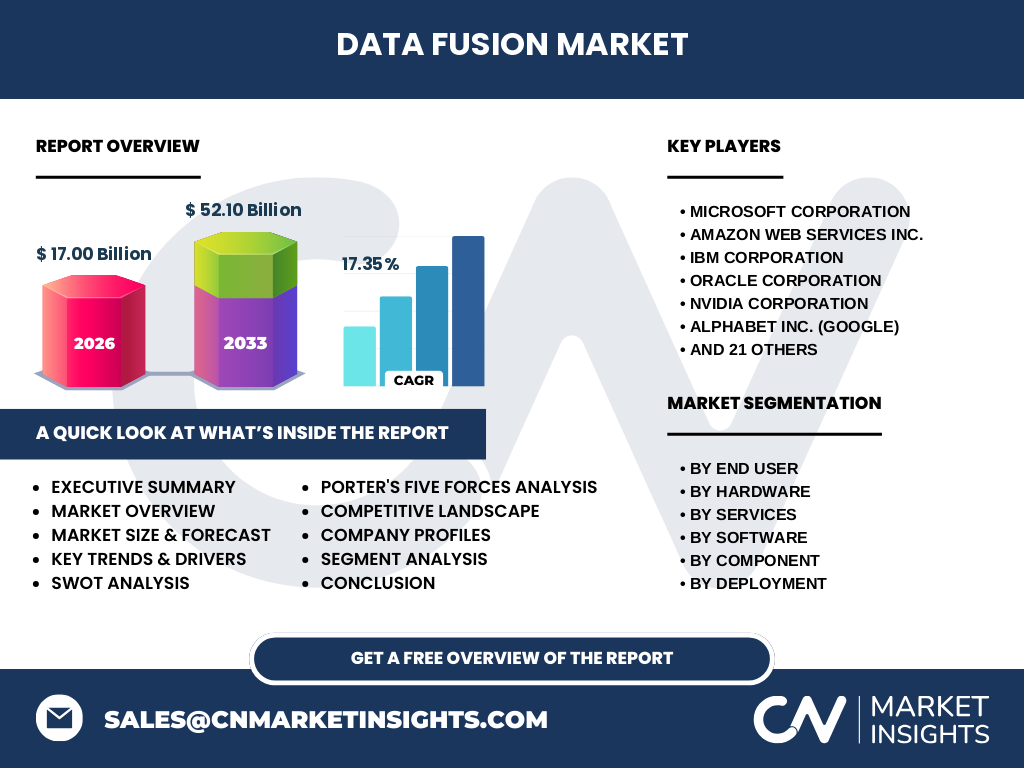
What is the scope and industry significance of the Data Fusion Market?
Our analysis indicates that the Data Fusion Market is valued at $17.00 Billion in 2026. This sector encompasses the integration of multiple data sources to produce more consistent, accurate, and useful information than any individual source could provide. Key industry participants leverage advanced AI/ML-based fusion platforms to drive operational intelligence across defense, financial services, and healthcare verticals.
Structural Growth Drivers and Market Constraints in the Data Fusion Market
The market is propelled by exponential data generation from IoT sensors and edge computing devices. However, severe regulatory constraints under GDPR and HIPAA, combined with the logistical hurdles of standardizing disparate data pipelines, act as restraints. Industry leaders like Palantir Technologies Inc. and Microsoft Corporation continuously innovate to overcome these integration bottlenecks.
Emerging Technological Shifts and Growth Patterns in Data Fusion
The shift toward real-time data processing software and edge intelligence is redefining architectural paradigms. Enterprises are increasingly adopting cloud-based systems and high-performance computing hardware (GPUs) to process mission-critical telemetry instantly. This trend favors agile software vendors capable of delivering low-latency, scalable analytics and visualization tools without compromising data governance standards.
Pandemic Aftermath: COVID-19 Impact Analysis on Data Fusion Adoption
The pandemic accelerated digital transformation initiatives, compelling organizations to adopt robust data integration software to ensure business continuity. Supply chain disruptions highlighted the critical need for resilient data acquisition systems and predictive analytics. Consequently, post-pandemic recovery trajectories for the Data Fusion Market industry trends show accelerated investments in automated decision support software.
Competitive Benchmarking and Strategic Dynamics in Data Fusion
The competitive landscape features a distinct divide between defense contractors like Lockheed Martin Corporation and RTX Corporation, and enterprise tech giants such as Alphabet Inc. (Google) and Amazon Web Services Inc. Market concentration is moderate to high, with strategic mergers focused on acquiring proprietary sensor fusion software and expanding managed services capabilities to capture lucrative government contracts.
Executive Summary of the Data Fusion Market Report
Our comprehensive report reveals that the Data Fusion Market is poised for explosive expansion, scaling from $17.00 Billion in 2026 to $52.10 Billion by 2033. Achieving a robust CAGR of 17.35%, the market's trajectory is anchored by surging demand for AI-driven insights, multi-sensor integration in autonomous systems, and stringent enterprise security requirements globally.
Market Forecast Projections from 2027 to 2033
Driven by compounding enterprise reliance on actionable intelligence, our projections indicate the market will expand rapidly over the 2027-2033 forecast period. Reaching the projected $52.10 Billion valuation at a 17.35% CAGR requires stakeholders to prioritize scalable cloud and edge infrastructure investments to capture high-growth opportunities across manufacturing and healthcare verticals.
Segmentation Analysis: Breaking Down Components, Software, and End Users
The market breaks down by component into Software, Hardware, and Services. Key segments include: Government, BFSI, Healthcare, Retail, and Manufacturing for End Users; Sensors, Edge Computing Devices, and GPUs for Hardware; Data Integration and AI/ML Platforms for Software; and Cloud and Edge for Deployment. Each segment plays a vital role in addressing unique industrial telemetry and compliance requirements.
Geographic Distribution and Regional Performance Overview
Regional performance varies significantly, with North America leading due to high defense spending and advanced IT infrastructure. Meanwhile, the Asia-Pacific region exhibits the fastest adoption rates, propelled by rapid industrialization, smart city initiatives, and surging investments in telecommunications. Regulatory environments in Europe shape localized compliance-driven deployments across financial and healthcare sectors.
In-Depth Regional Review of High-Growth Geographies
North America remains the revenue epicenter, anchored by major defense primes and tech innovators like IBM Corporation and Oracle Corporation. Concurrently, the European market prioritizes data sovereignty and privacy, creating high demand for secure on-premises systems and specialized middleware solutions. Asia-Pacific showcases massive growth potential fueled by extensive manufacturing automation and 5G rollouts.
Company Profiles and Strategic Positioning of Leading Market Participants
Industry titans such as NVIDIA Corporation provide vital GPU hardware, while defense leaders like BAE Systems plc and Thales SA specialize in mission-critical tactical data fusion. Enterprise software vendors like SAP SE and specialized analytics firms like K2view Ltd. deliver robust data management solutions, collectively shaping a diverse, innovation-driven competitive ecosystem.
Porter's Five Forces Analysis of the Data Fusion Industry
Competitive rivalry is intense among established cloud and defense giants. Supplier power remains moderate, governed by specialized hardware and GPU availability. Buyer power is high due to enterprise demand for customized solutions. The threat of substitution is low given the complex nature of AI/ML fusion platforms, while the threat of new entrants is mitigated by high R&D entry barriers.
SWOT Analysis: Internal Strengths and External Market Dynamics
Key strengths include advanced algorithmic capabilities and robust multi-source ingestion. Weaknesses involve high implementation costs and integration complexity. Opportunities lie in IoT expansion and autonomous vehicle telemetry. Threats include escalating cybersecurity vulnerabilities, strict cross-border data transfer regulations, and proprietary data silos enforced by legacy incumbents.
Value Chain Analysis from Raw Data to End-User Intelligence
The value chain flows from raw sensor raw materials and semiconductor manufacturing through data acquisition systems and integration software, culminating in end-user decision support. Companies adding high-end value through AI-based analytics capture the highest margins, whereas commodity hardware providers face intense price competition across global supply chains.
Investment Insights and High-Potential Strategic Areas
Investors should target niche innovators specializing in real-time edge processing and secure AI/ML-based fusion platforms. Strategic acquisitions of firms holding proprietary defense or healthcare data integration patents offer high upside. Focus should remain on scalability, compliance readiness, and interoperability with legacy enterprise systems.
Conclusion and Strategic Takeaways for Industry Stakeholders
The trajectory of the Data Fusion Market analysis underscores an essential shift toward real-time, AI-driven intelligence. With market size surging to $52.10 Billion by 2033, organizations must modernize their data infrastructure, embrace edge computing, and forge strategic partnerships to maintain competitive advantage in a data-saturated global economy.
Research Methodology and Baseline Triangulation Techniques
Our baseline estimates are rigorously triangulated by combining trade registry data, primary stakeholder interviews with CTOs and defense contractors, and secondary macroeconomic indicators. This multi-layered research methodology ensures high fidelity in sizing market segments, forecasting growth trajectories, and validating competitive market shares across all specified geographies.
Scope of the Report, Coverage Parameters, and Analytical Limitations
This report covers global market dynamics from 2026 to 2033, analyzing quantitative revenues and qualitative trends across defined software, hardware, services, deployment, and end-user segments. Limitations include unforeseen macroeconomic shifts, geopolitical trade friction, and rapidly evolving regulatory frameworks governing cross-border data flows.
Recent Developments: Strategic Partnerships, Product Launches, and Market Moves
Recent industry developments highlight aggressive strategic maneuvers, including cloud-defense partnerships between tech giants and prime contractors like General Dynamics Corporation and Leidos Holdings Inc. Investments in generative AI integration and edge processing capabilities dominate corporate announcements, signaling accelerated commercialization of advanced sensor fusion software worldwide.